Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
- Straits Trading Company (“STC”) saw a drop in EBITDA in 1H23, largely due to the disposal of ARA Asset Management in 1H22. Excluding this one-off gain, EBITDA and PATNCI improved in 1H23.
- We retain our positive view on the Group’s outlook. We expect STC to remain profitable and earnings to gradually rebound on the back of a stronger macro backdrop.
- Credit profile remains healthy due to a prudent leverage profile, strong liquidity, and a generally stable cashflow.
- We recommend the STRTR 4.100% 04May2026 Corp (SGD) and STRTR 3.750% 29Oct2025 Corp (SGD).
Company Background
The Straits Trading Company Limited (“STC”) is a conglomerate-investment company with operations across various business segments such as resources, real estate, and hospitality. The Group reports revenue in these three operating segments.
STC operates a large property segment comprising of developers and real estate investment companies such as Straits Development Pte. Ltd., STC Property Management Sdn. Bhd., Straits Real Estate Pte. Ltd., and Straits Investment Management Pte. Ltd. The Group also owns a minority interest in ESR Cayman Limited, which is APAC’s largest real estate and real assets fund manager, and Suntec REIT, one of the largest commercial REITs in Singapore.
The Group’s resources segment is driven by its 52%-owned subsidiary, Malaysia Smelting Corporation (“MSC”), which is listed on both the Singapore Exchange and Bursa Malaysia. The Group’s hospitality segment is mainly driven by Far East Hospitality Holdings Pte Ltd (“FEHH”), which is a 30%-owned joint venture with Far East Orchard Limited.
Financial Highlights
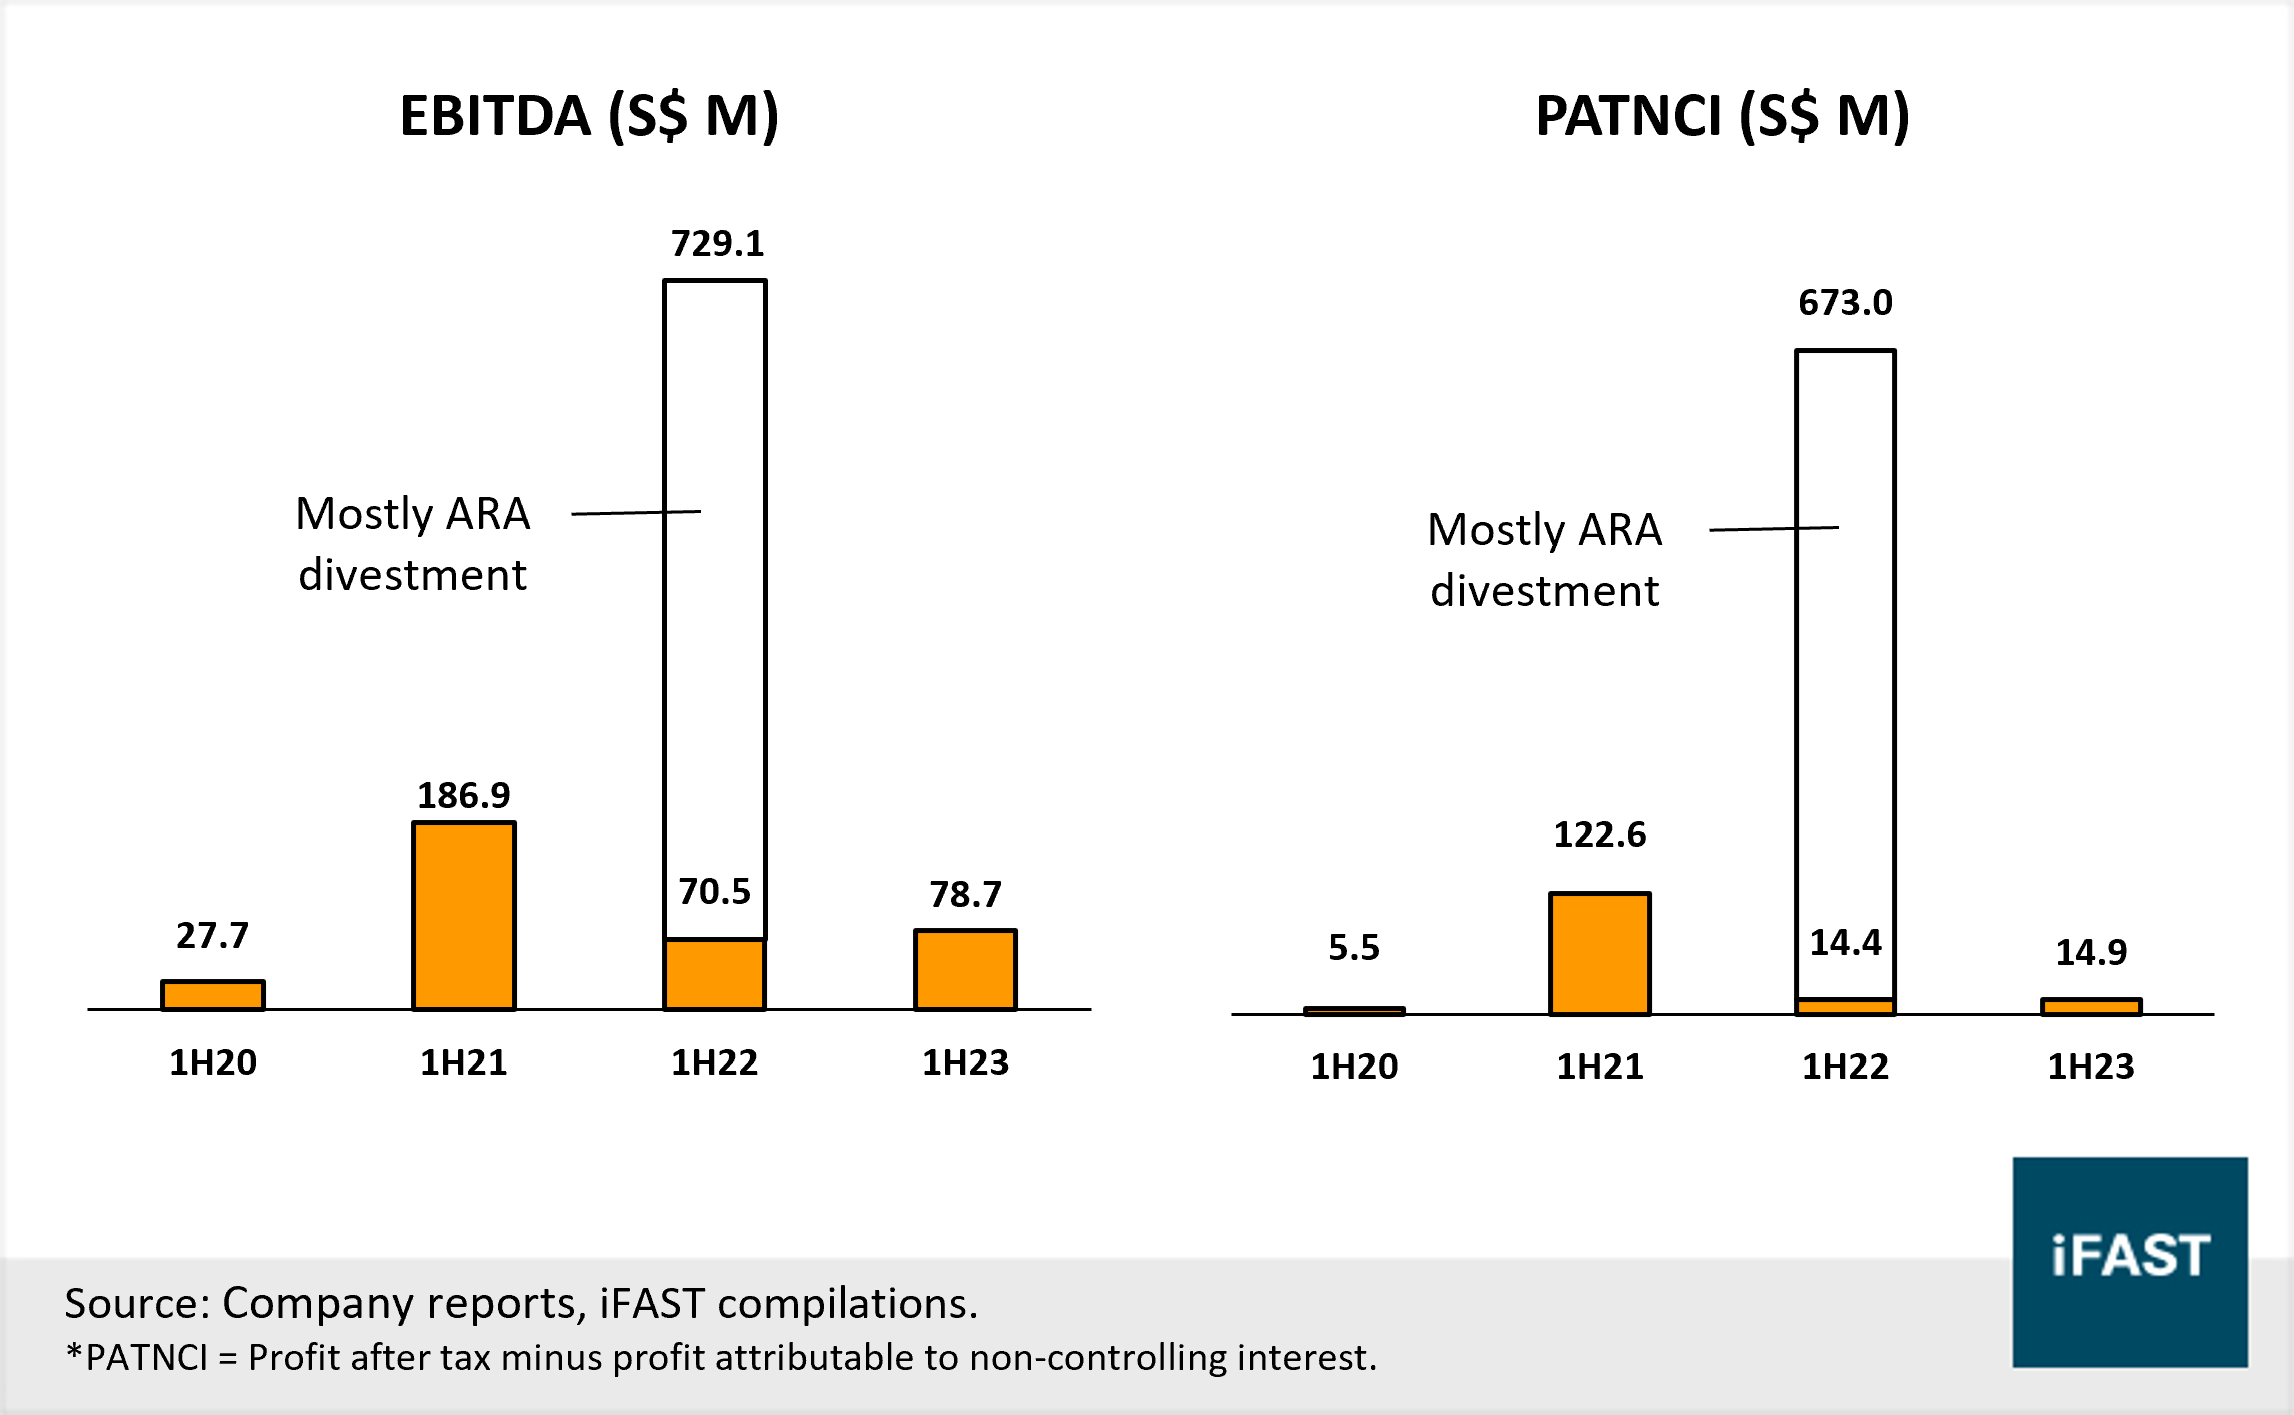
For the six months ended 30 June 2023 (“1H23”), STC’s revenue fell 12.7% year-on-year (YoY) to S$235.8M (Chart 1) as the Group saw a drop in revenue across its operating segment. At a glance, EBITDA fell -89% YoY to S$78.7M in 1H23. However, this was due to a large one-off gain from the disposal of ARA Asset Management which catapulted EBITDA in 1H22. Excluding this one-off gain, EBITDA increased 11.7% YoY while PATNCI (profit after tax minus profit attributable to non-controlling interest) grew 3.5% YoY to S$14.9M.
The Resources segment reported a 35.7% YoY decline in EBITDA to S$32.9M in 1H2023 due to lower average tin prices despite higher sales quantity. With management staying cautious on the outlook for the resources segment due to macro headwinds like tight monetary policy and inflation, MSC will continue to focus on operational efficiencies and improving output for tin smelting and mining. Smelting operations are expected to achieve higher operational efficiency and lower costs moving ahead.
The real estate segment reported a moderate 14.6% YoY decline in EBITDA to S$26.9M in 1H2023, less the one-off gains mentioned above, larger due to higher finance costs. That said, we note that rental income from its investment properties portfolio remains resilient and has increased by 36.5% YoY to S$33.7 million in 1H2023. Across the Group’s investment properties, a significant 86% of the properties are operational and income-generating while assets appear to be well-diversified across Singapore, S. Korea, UK, Japan, China, Malaysia, and Australia.
Management expects the completion of Straits City Phase 1 by 1Q24, a project that sits on prime land in Penang. This project is expected to benefit from a potential rise in land value as the government’s recently announced "Accelerating Penang2030" gradually materialises, proving supportive for earnings of the real estate segment.
The Hospitality segment registered an EBITDA loss of S$0.3M in 1H2023, largely driven by currency translation losses. That said, STC’s hospitality business has recovered to near pre-COVID levels as travel demand surged over the past year. New openings in 2H23, including Adina Serviced Apartments in Vienna and a new hotel in Australia, may help support the segment’s revenue moving forward. Meanwhile, management is also targeting to achieve a goal of 25,000 rooms goal by 2025.
Chart 1: EBITDA and PATNCI grew YoY, excluding one-off gain from the disposal of ARA Asset Management
Business Outlook
We retain our positive view on the Group’s outlook since our prior credit update. While earnings have fallen, we note that 1H22 earnings were enlarged by a one-off asset disposal, and expect the Group to remain profitable and earnings to gradually rebound on the back of a stronger macro backdrop. We see multiple drivers of earnings in the
- Real estate segment, supported by resilient rental income as global economic activity recovers, and major developments like Straits City;
- Resources segment, largely driven by higher sales quantity and lower costs; and
- Hospitality segment, which should remain profitable on an annualised basis, and we see scope for improved earnings given new openings – 5 hotels and 1 service apartment in 2023 – and a continued tourism rebound.
Credit highlights
The Group’s debt profile remains healthy despite higher leverage. For the six months ended 30 June 2023, total borrowings rose 15% HoH to S$1.6B. However, a majority of the increase came from long-term secured borrowings (primarily from bond issuance), which grew 60% HoH, while short-term borrowings declined by -46% HoH. Short-term borrowings amounted to S$0.18B, of which nearly S$0.12B are secured, with mortgages on selected properties, other assets, and shares in certain subsidiaries.
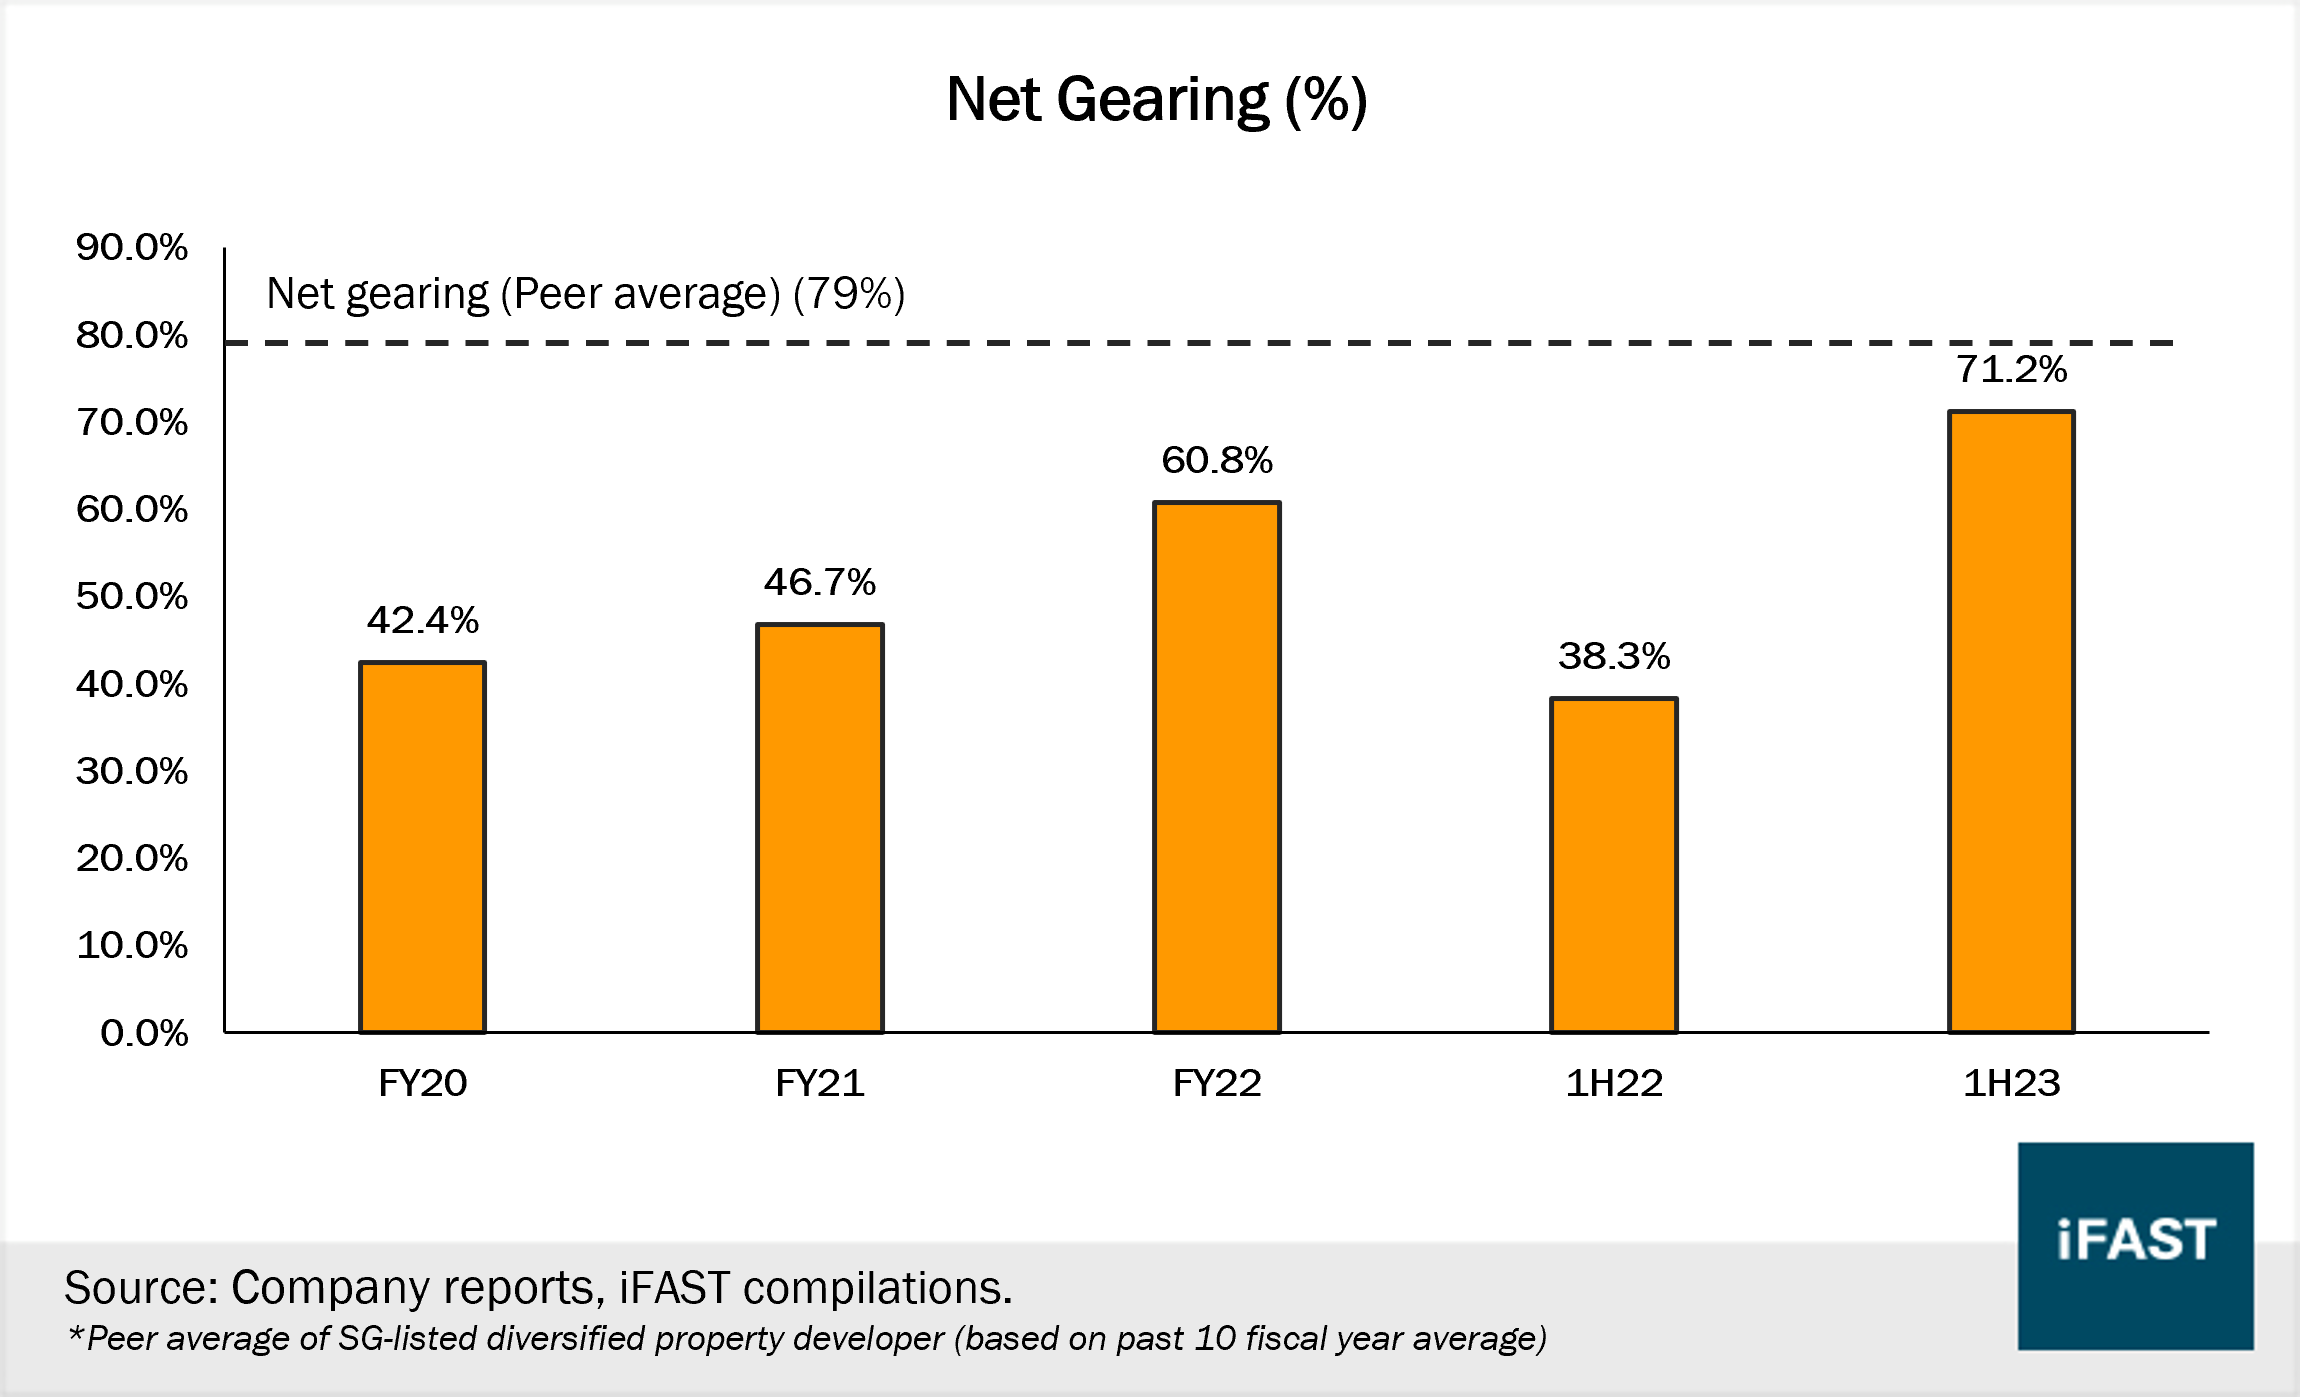
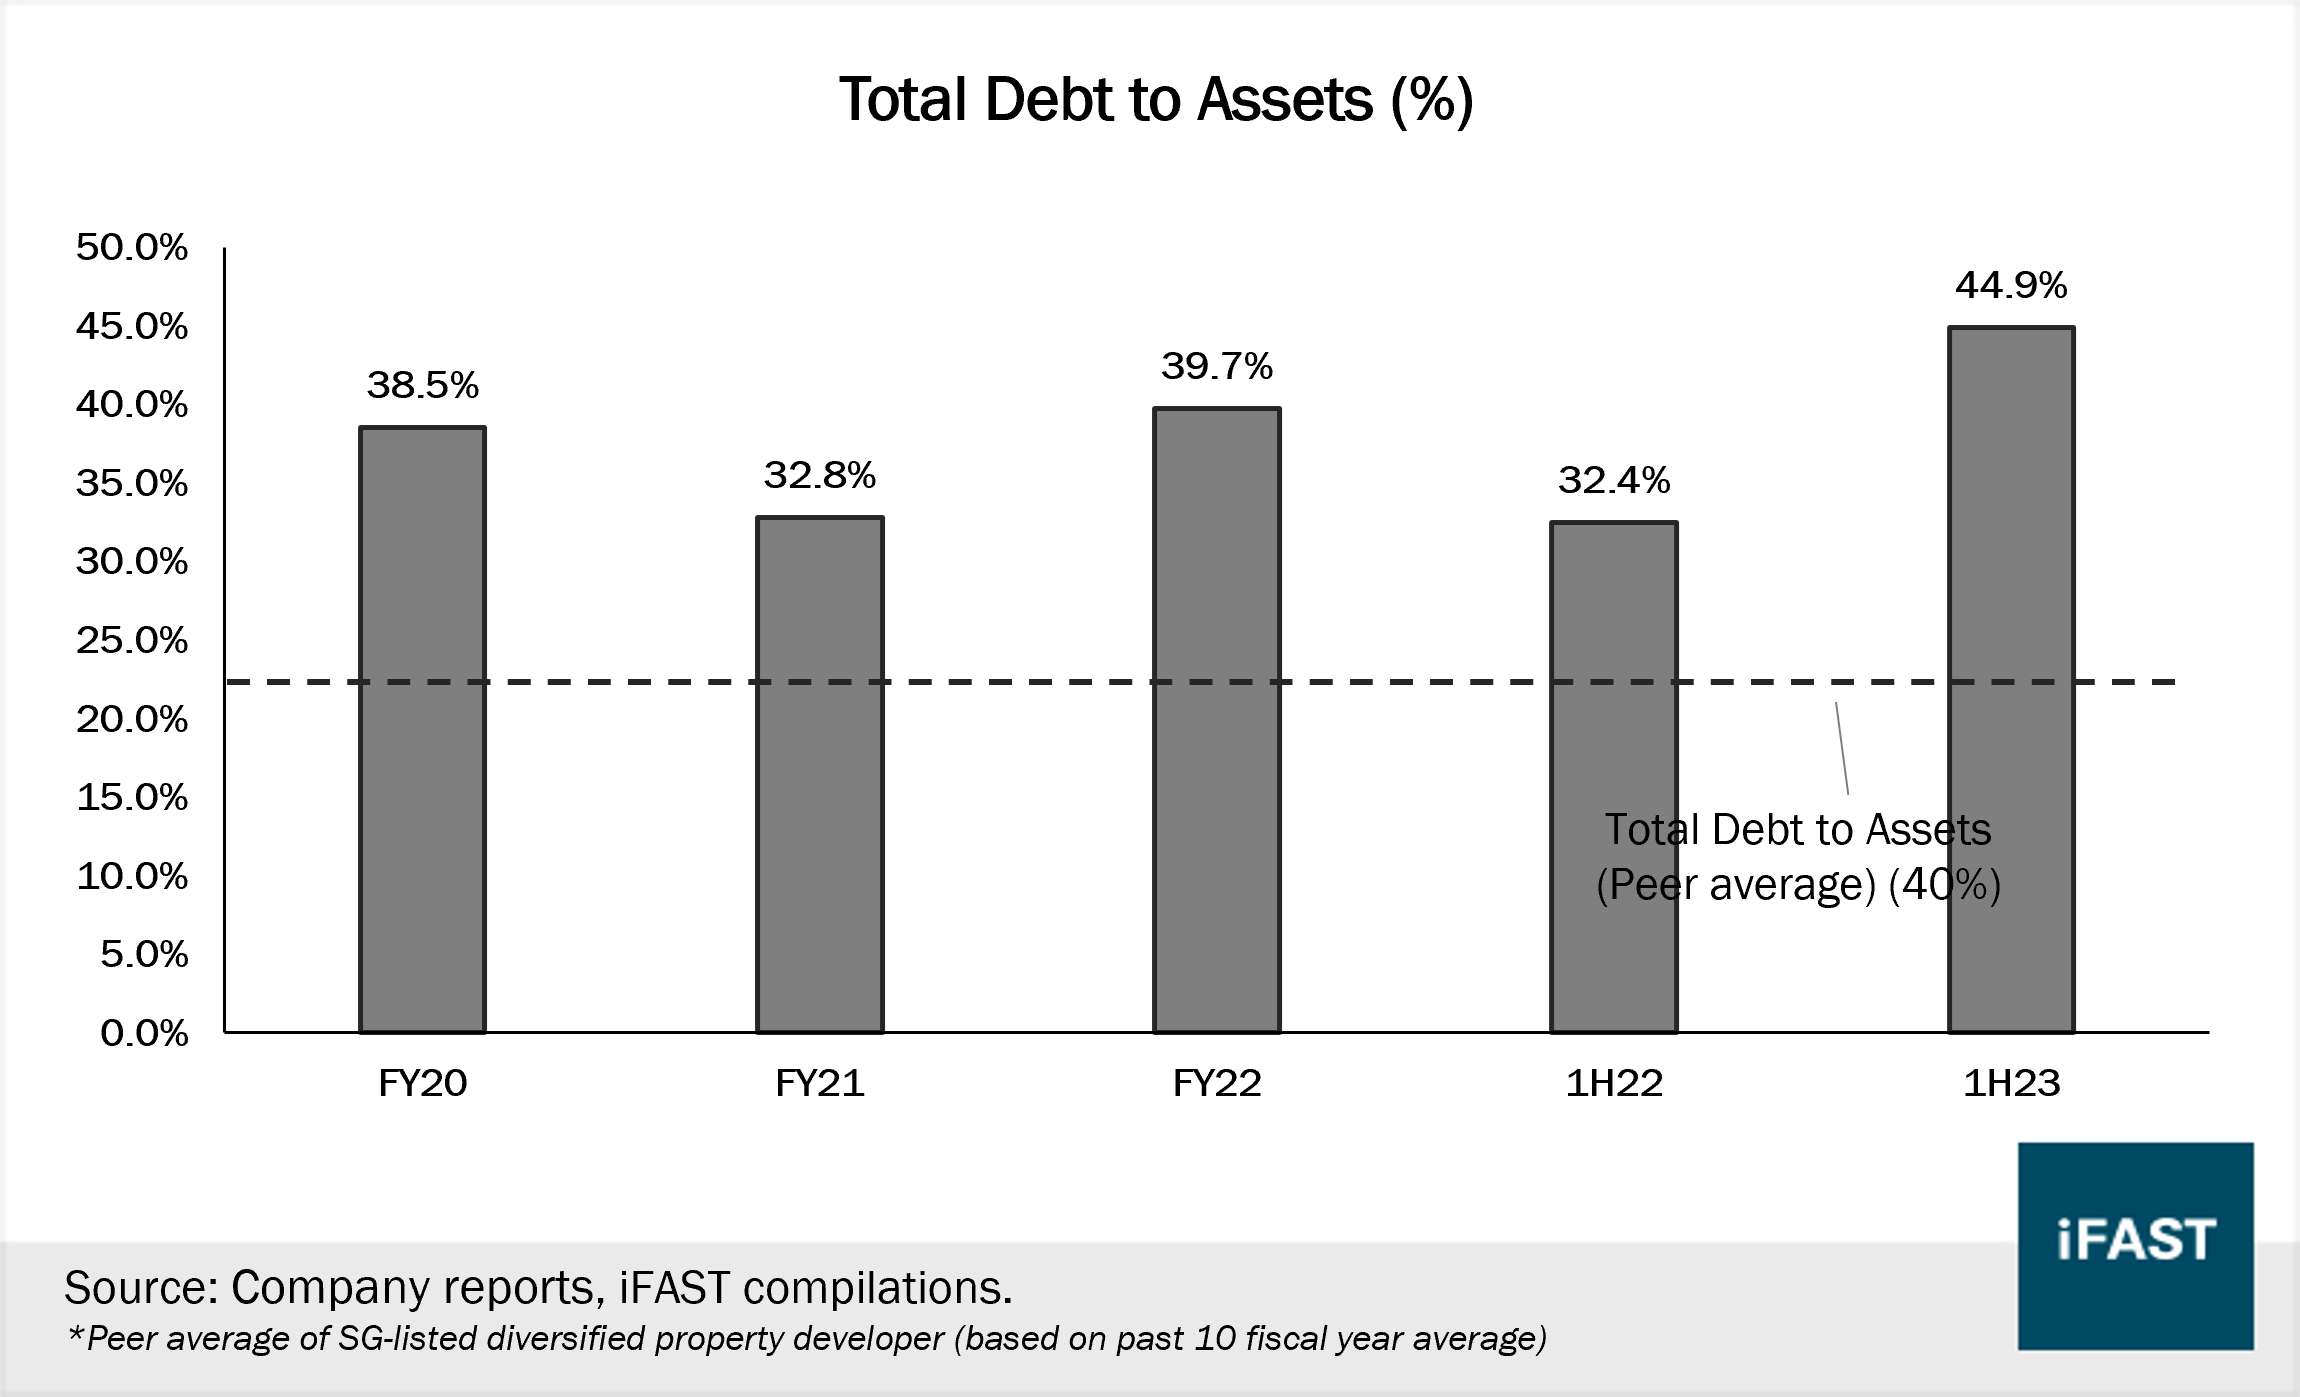
The Group’s capital structure remains prudent in our view, with a total debt to asset ratio of 35% while the net gearing ratio was estimated to be 71% in 1H23. Both ratios saw a slight uptick from 2H22, as a result of higher leverage and modestly lower equity but remain in line with the peer average (Chart 2 and 3).
Chart 2: While net gearing has risen, it remains below the peer average
Chart 3: Total debt to asset ratio has ticked up but not much higher than the peer average
Nonetheless, the Group’s debt coverage has deteriorated as EBITDA coverage declined to an estimated 1.9x in 1H23. EBITDA coverage ranged from 3.8x to 6.0x before Covid from FY17 – FY19. This weakening of debt coverage was due to softer EBITDA and higher finance costs, which have risen by more than two-fold to S$40.6M, largely due to higher interest rates and the issuances of exchangeable bonds. We do not see this as a red flag at the moment as we expect EBITDA to gradually improve and for finance costs to eventually normalise.
The Group continues to improve its liquidity position by growing cash and cash equivalent to S$354M in 1H23 from S$252M in 2H22, helped by the issuance of exchangeable bonds and drawdown of loan facilities. Cash and cash equivalent being nearly twice the sum of short-term borrowings in 1H23 also provides sufficient short-term coverage. We think the company has decent channels of liquidity given unutilized credit lines, strong banking relationships with lending banks, easy access to debt markets, and a good track record of asset disposal which can generate substantial cash inflows.
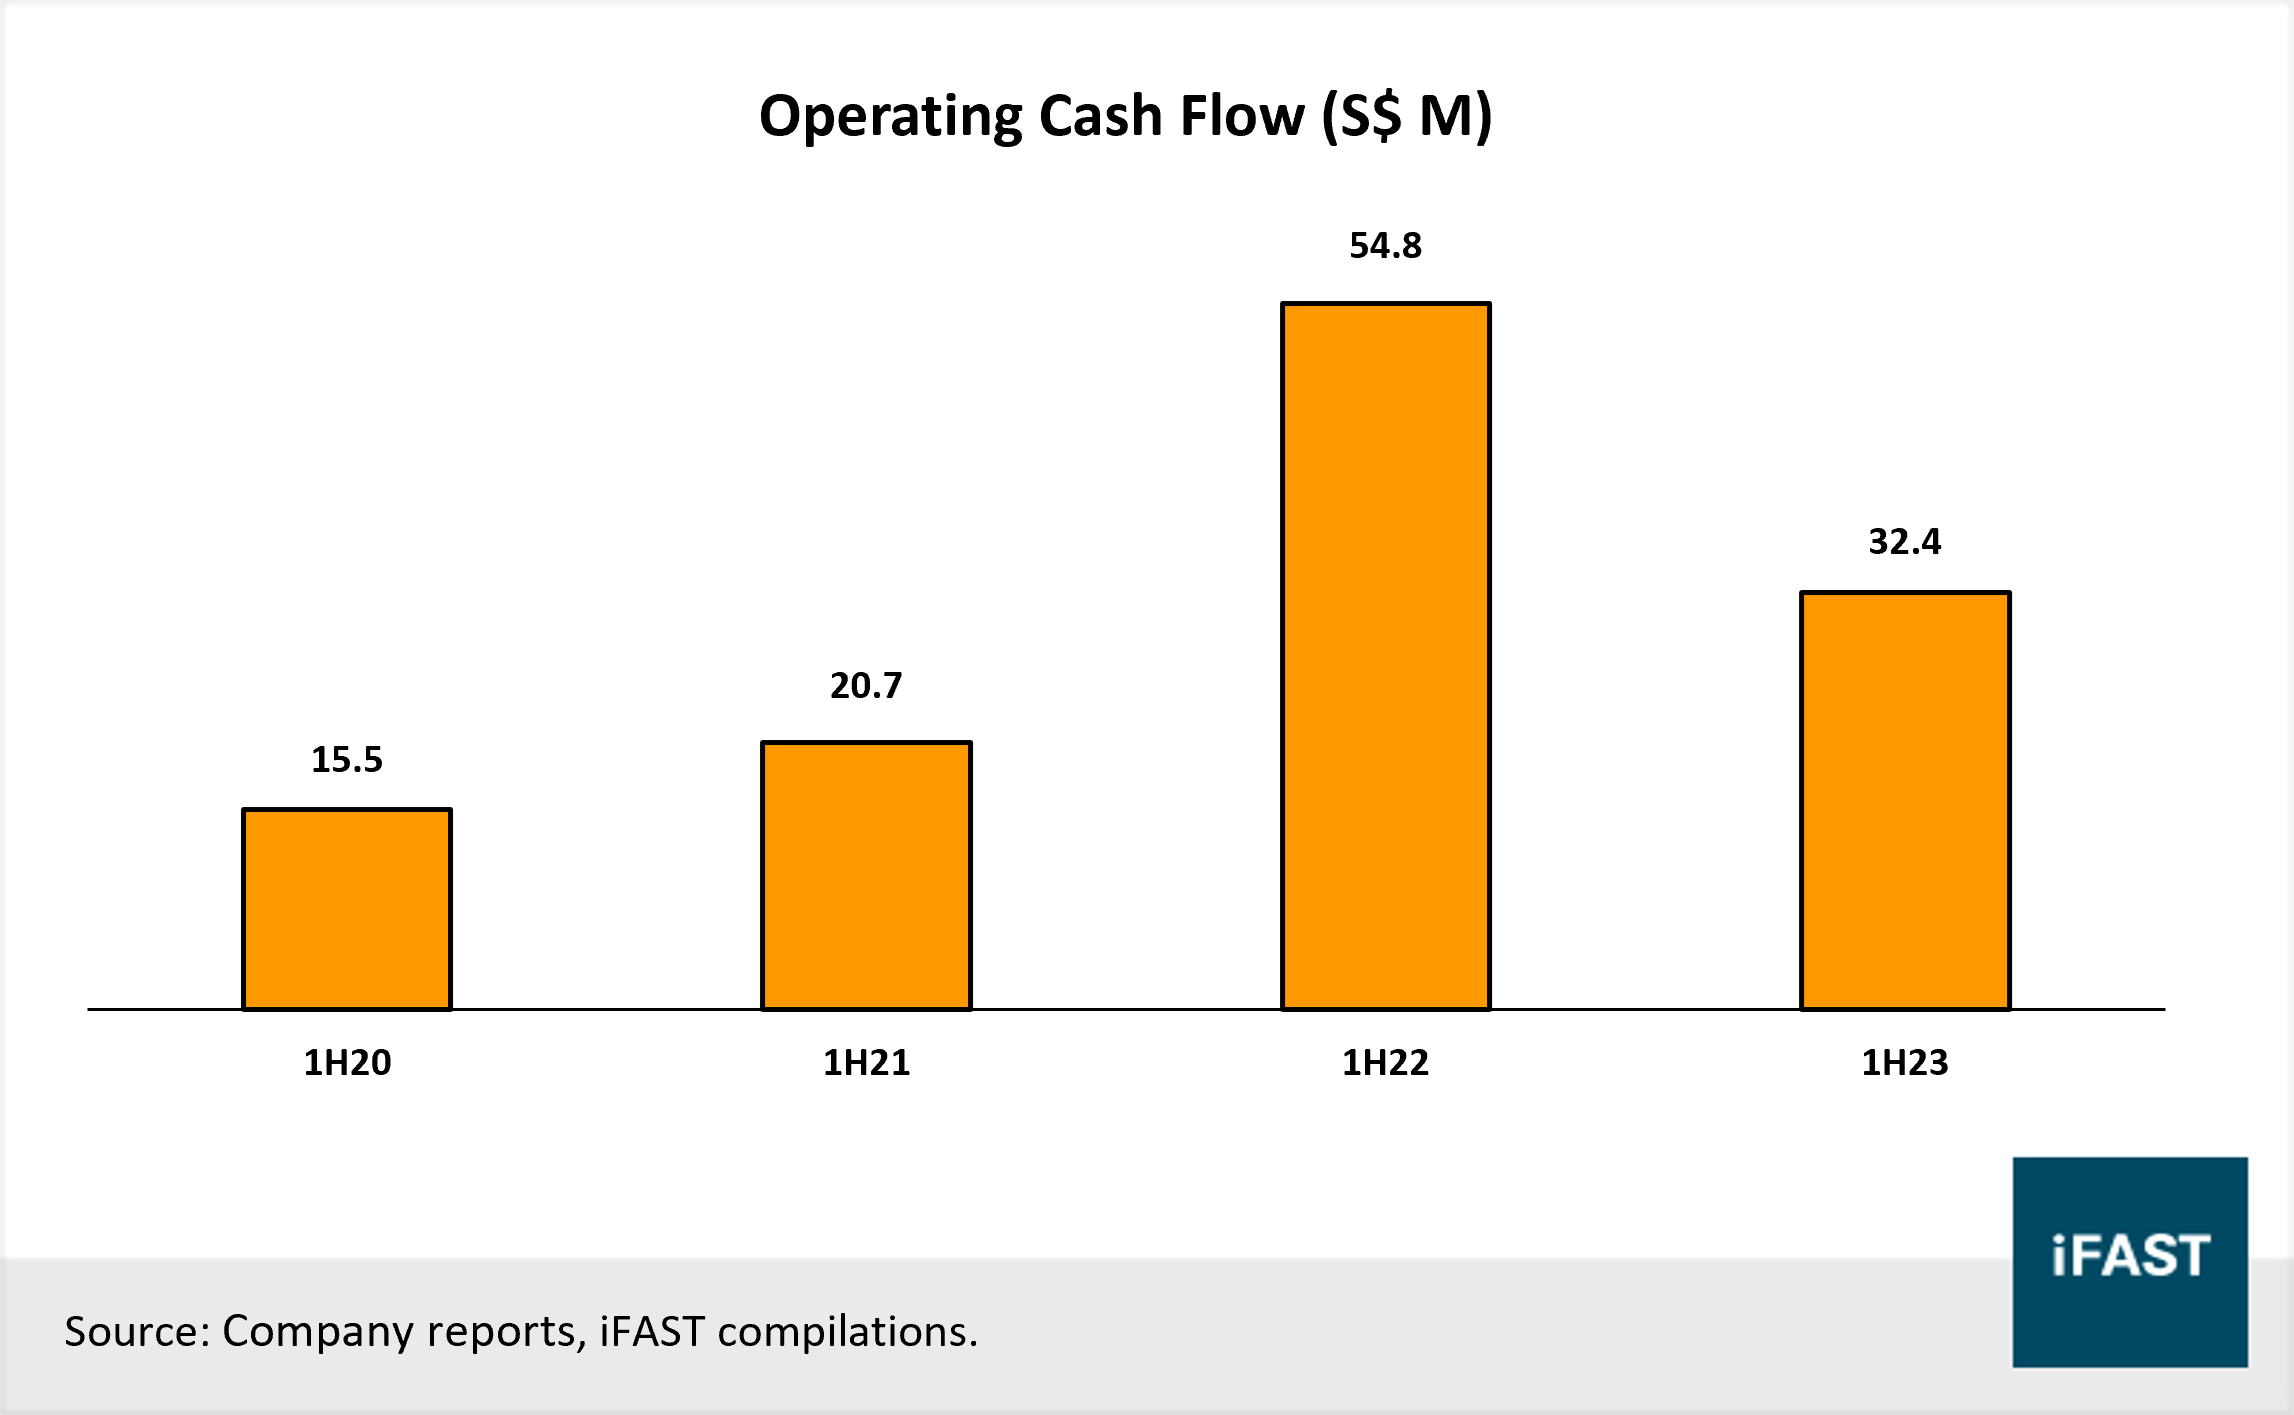
Operating cashflow has normalised from 1H22, which was an exceptionally strong year of profits, but remains higher at S$32.4M as compared to 1H21 and 1H20. The Group has multiple sources of cashflow that are recurring (such as dividends from investment securities and interests) which helps to stabilise cashflow across property cycles.
Chart 4: Operating cashflow has normalised but remains healthy
Recommendations
Table 1: Unrated fixed rate issuances from Straits Trading and comparable peers
As compared to our previous update, the Group’s credit profile has moderated, largely due to softer profits and weaker coverage. However, it remains healthy due to a prudent leverage profile, strong liquidity, and a generally stable cashflow. A gradually improving EBITDA should also improve credit metrics over time.
Amongst STC’s fixed rate issuances, we prefer the STRTR 4.100% 04May2026 Corp (SGD) and STRTR 3.750% 29Oct2025 Corp (SGD) (Table 1). Both bonds screen as attractive short-term SGD options for investors given the higher yields as compared to its peers with similar years to maturity. Between both, STC’s 2026 bond offers a ~12bps pickup over its 2025 bonds for an additional 0.51 years which we consider decent and suitable for investors who want to lock in higher yields.
We think the newly issued STRTR 4.700% 24Jan2029 Corp (SGD) which is trading above par and yielding ~4.48% (YTM) is looking less attractive amongst STC’s issuances after the recent drop in yield.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds positions in STRTR 3.750% 29Oct2025 Corp (SGD), STRTR 4.100% 04May2026 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!